Sell a Flood-Damaged House in Charleston
Water in the house after a king tide or a storm? We buy flood-damaged and flood-prone houses across the Charleston area as-is, with full disclosure and no repairs on your end.
Get My Cash Offer Call (727) 300-6656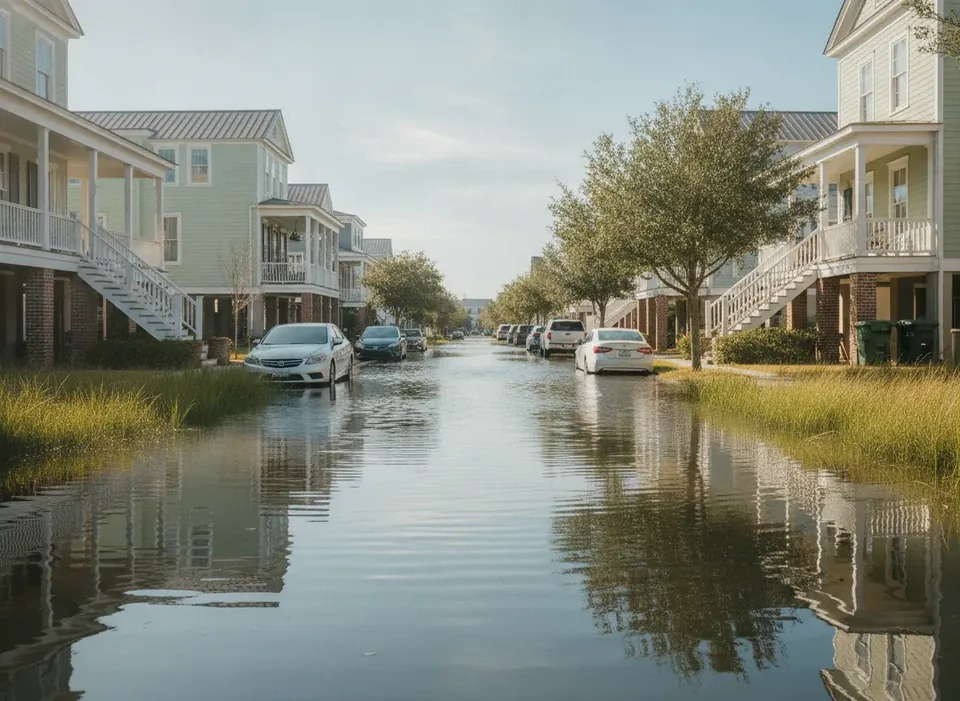
Flooding is part of owning a home in Charleston
The National Weather Service office in Charleston counts a coastal flood event when Charleston Harbor reaches its 7-foot (MLLW) flood stage. In the 1980s that happened fewer than 10 times a year. Since 2020 it has averaged 57 times a year. News reporting of NWS figures put 2019 at a record of about 89 tidal flood events and 2025 at about 52.
Storms add to it. Hurricane Matthew pushed Charleston Harbor to a 9.29-foot storm tide in October 2016, and Irma reached 9.92 feet in September 2017 (NWS Charleston). For many low-lying homes, the real question is whether you want to keep repairing.
The flood questions on South Carolina's disclosure form
Since June 1, 2023, the South Carolina Real Estate Commission's Residential Property Condition Disclosure Statement asks sellers directly about water and flooding. The current form asks about:
- Water problems, including whether any structure has flooded from rising water or water intrusion while you've owned it
- Erosion and erosion-control structures such as seawalls
- Flood hazards, wetlands, flood zone designations and flood risk
- Whether the property has public (NFIP) or private flood insurance
- Flood insurance claims, with dates, repairs and amounts
- Flood repairs you paid for without filing a claim
- Federal flood disaster aid received, such as FEMA, SBA or HUD assistance, with the amount and purpose
Selling to a cash buyer doesn't exempt you. We will never tell you to skip disclosure, and you shouldn't trust any buyer who does. The form warns that an owner who knowingly fails to disclose a problem may be liable for damages, and checking “no representation” doesn't erase that. The form can be waived only if buyer and seller both agree in writing, or if another exemption in the statute applies, such as certain court-ordered or estate sales.
This is general information, not legal or tax advice. Ask your own attorney how to answer each question. For more background, read flood disclosure and king tides in Charleston.
Flood insurance claims, FEMA aid and what to gather
Gather what you have:
- Flood insurance declarations and any claim letters
- Dates of each flood and what was repaired, with receipts
- Any FEMA, SBA or HUD disaster aid paperwork
- An elevation certificate or flood zone determination, if you have one
These answer the disclosure questions and let us price on facts. If you received federal aid, ask your attorney whether any conditions attached to it affect a sale.
One more rule matters for heavily damaged homes in a flood zone. Under the City of Charleston's floodplain rules, an existing home in the Special Flood Hazard Area that is substantially damaged, generally meaning repairs that cost 50% or more of the structure's value, may have to be brought fully into floodplain compliance, which can mean elevating it. That rule often turns a repair job into a decision to sell.
City buyouts vs. a cash sale
The City of Charleston runs a voluntary buyout program funded mainly by FEMA grants. As of 2026, the City says it has acquired 46 properties in James Island and West Ashley and returned the land to green space. One example is Bridge Pointe in West Ashley's Church Creek basin, where 32 flood-prone townhomes were bought out and demolished; the site is now Bridgepointe Ecological Park.
If you might qualify, look into it. But buyouts depend on grant funding, they prioritize repetitive-loss and substantially damaged homes, and the City notes there is no set timeline. Drainage work is underway too, such as a $4.5 million final phase of the Central Park basin project on James Island, which Live 5 News reports is expected to finish by the end of 2027. A cash sale is another option you can compare.
The honest price trade-off
Our cash offer will usually be less than what you might get listing with an agent after repairs. That's the trade for speed, certainty, no repairs and no fees. Use our cash offer vs. listing calculator to compare, and feel free to get an agent's opinion too.
A flood history affects any buyer's price, ours included. We price the house as-is from a repair estimate, comparable sales and what we need to resell, and we explain each number.
How we buy flood-damaged houses
Tell us about the house
Use the form or call. Share what you know about the house and your timing; you don't need contractor quotes or a cleaned-up house.
Get a written cash offer
We'll send a written cash offer within 24–48 hours of seeing the house or getting the details we need, with an explanation of how we got there.
Disclosure and title
You complete the disclosure statement, or we both agree in writing to waive it. The closing attorney runs the title search and lines up any mortgage payoff from the sale proceeds.
Close on your date
We can close in as little as 7–14 days when the title is clear, at a South Carolina attorney's office, or later if that suits you. No fees or commissions, and we pay the closing costs.
See how it works.
Flood-prone areas we buy in
We buy flooded and flood-prone houses in:
Related situations: selling a house that needs repairs and selling an inherited house. Also see SC seller disclosure in an as-is sale.
Frequently asked questions
Do I have to disclose flooding when I sell my house in South Carolina?
In most sales, yes. Since June 2023 the SC Real Estate Commission's disclosure form asks about past flooding, flood zones, flood insurance, claims and federal disaster aid. Selling to a cash buyer doesn't remove that duty. The form can be waived only by written agreement of both parties or under an exemption listed in the statute. This is general information, not legal advice; ask your attorney.
Can I sell a house that has flooded more than once?
Yes. We buy houses with repeat flooding, including homes with open repairs, mold or water-damaged drywall. We'll ask for the flood history, insurance claims and any aid received so we can price the house honestly. You don't need to tear out or repair anything first, and you'll get a written cash offer within 24–48 hours of us seeing the house.
Should I wait for a City of Charleston buyout?
If your home may qualify, a buyout can be worth pursuing, so contact the City's program. Buyouts are voluntary, depend on FEMA and state grant funding, prioritize repetitive-loss and substantially damaged homes, and the City says there is no set timeline. If you need to move sooner, compare a buyout's likely timing with a written cash offer.
Does flood insurance or FEMA aid affect selling my house?
It shapes what you disclose: the state form asks about flood insurance, claims, repairs and federal aid amounts. Raise any open claim or conditions attached to aid with your insurer, lender and attorney before closing. We don't give legal or tax advice, but having that paperwork ready helps us make an accurate offer and keeps the closing on schedule.
Will you pay less because the house floods?
Any buyer factors flood history into price, and our offer will usually be less than you might get listing after repairs. In exchange you skip repairs, cleanup, showings and commissions, and we pay the closing costs. We explain our numbers: the as-is condition, a repair estimate, comparable sales and what we need to resell the house.
Ready for a no-obligation cash offer?
Tell us about the house. We usually reply the same day, and you choose the closing date.